
The International Monetary Fund has called on Britain, the United States and other advanced economies to rein in debt as the Middle East energy shock adds to inflationary pressures and pushes up government borrowing costs.
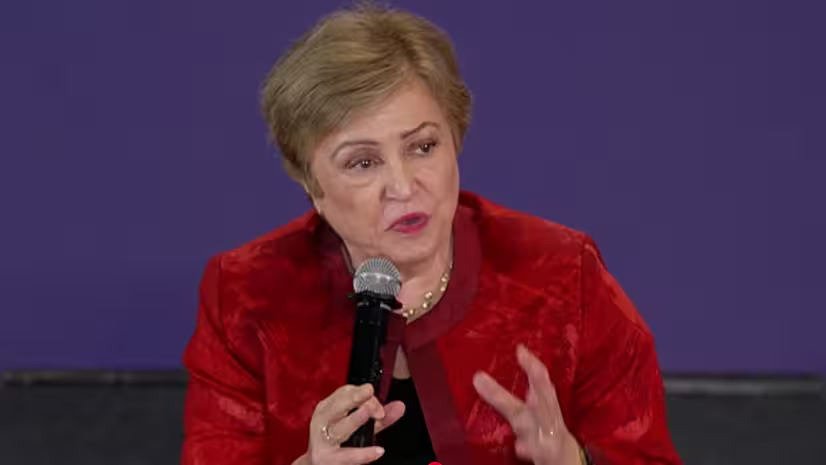
Kristalina Georgieva, the IMF’s managing director, says a series of global shocks have been “pushing debt levels up like a staircase not to heaven” while governments have taken “no action to contain that service cost”.
“[It’s] time to take that action,” she said, adding that “courage” was needed from politicians to make difficult decisions.
Speaking during the United Nations General Assembly in New York, Georgieva said governments need to bring down debt while central banks continue efforts to control inflation.
She said: “There are these two things that must be done: bring debt levels down, put fiscal consolidation as a priority, and make sure that the central banks deliver on their mandate for price stability.”
Georgieva added: “It is impossible to stress strongly enough how critical it is to get the courage to take the steps that are necessary. These are politically tough steps to take, but necessary steps to take.”
Her warning comes as the war with Iran and disruption to energy flows through the Strait of Hormuz continue to put pressure on inflation and government financing costs.
The global economy has remained resilient despite oil trading at about $100 a barrel, but Georgieva warns that the effects of the energy shock have yet to pass.
At Semafor’s Next 3 Billion event in New York, she said: “Winter is coming.”
The Strait of Hormuz remains largely closed, while strategic oil and gas reserves depleted during the disruption will eventually have to be rebuilt.
Persistent inflation is keeping monetary policy tighter, leaving governments with higher costs for servicing their debts.
The US national debt has surpassed $40 trillion, roughly double its level a decade ago.
Britain is also under fiscal pressure ahead of Prime Minister Andy Burnham’s first Budget next month. Government borrowing stood at £18.3 billion in August, almost 20 per cent higher than a year earlier and above official projections. Interest payments on government debt were the highest for any August since monthly records began in 1997.
Asked about the comparatively high cost of UK government borrowing, Georgieva said its position was “not very different” from that of other advanced economies.
She pointed to “fairly consistent action” on reducing debt and praised reforms to planning and housing. Georgieva said advanced economies “don’t have the cash” to boost growth and must instead use reforms to encourage private investment.
Emerging economies face a different challenge, with higher interest rates threatening to reverse improvements made to their public finances.
Georgieva said: “While many market economies have done miracles to reduce their debt levels, to put in place fiscal discipline and shrink spreads for their borrowing. Now what’s happening is interest rates go up, they’re washing away hard-earned gains in emerging markets. So it’s not competition for money, per se, but it’s the punishment for someone else’s sins that emerging markets have to bear.”
Investment in artificial intelligence is meanwhile helping to support economic growth, countering some of the effects of the energy shock.
Georgieva said the IMF does not yet see AI investment crowding governments out of debt markets, but added: “it’s possible this becomes a problem so we have to watch it.”
Georgieva said: “If we see more incidents when AI takes [on a] life of its own, then we can be faced with a significant financial stability risk.”
The IMF sees AI investment and the energy shock as competing forces affecting the global economy.
Georgieva said it was important for reduced oil and gas exports from the Gulf “to resume in a durable manner, for the energy supply shock to finally be in the rearview mirror”.
She added: “That is a very significant step to normalisation.”
Georgieva said: “We should prepare for people being more unhappy. Maybe on the street.”
